

 Buy a Licensed Company
 Explore VASP Data
 Talk to an Expert


Before you deposit: a due diligence pass on a crypto platform
“Checking a crypto platform before funding it is a procedure. Registration data, withdrawal terms, review distribution, and the signals that do not hold up.”
Three offset layers traced by a single line that bends at each misalignment

Due diligence on a crypto platform usually gets performed in the wrong order. The account is opened, a small amount goes in to see whether it works, and the checking starts once something feels off. By then the useful evidence is harder to read, because the reader has a position.
The procedure below runs before the first deposit. None of it requires specialist tooling and none of it is about whether a given asset is a good idea. It is about whether the counterparty is what it says it is.
Two things make the exercise tractable. The evidence is public, and the failure modes repeat. An overview of how fake crypto offers are built is useful background for that second point: a fabricated track record is assembled in recognizable ways, and knowing the construction makes the result easier to spot. Services such as WebVouch check that a reviewer actually transacted before the entry appears, and weigh how many reviews a business has and how evenly they arrived, rather than reducing everything to a star average.
Start with what is registered, not with what is claimed
A platform’s own description of its regulatory position is a marketing document. The registry entry is the primary source.
Three things are worth reconciling. The legal entity named in the terms of service, the entity named in any license or registration the platform cites, and the entity that actually receives the funds. These are frequently not the same, and the gaps are not always improper. A platform operating through a subsidiary in a different jurisdiction may be doing so for ordinary reasons. The point is to know, before depositing, which entity you can claim against.
Where a registration is cited, check its scope rather than its existence. A money services registration is not a license to custody assets, and a sandbox authorization is not a full license. Platforms are rarely dishonest about this in their filings and frequently imprecise about it in their marketing.
Read the withdrawal terms before the deposit terms
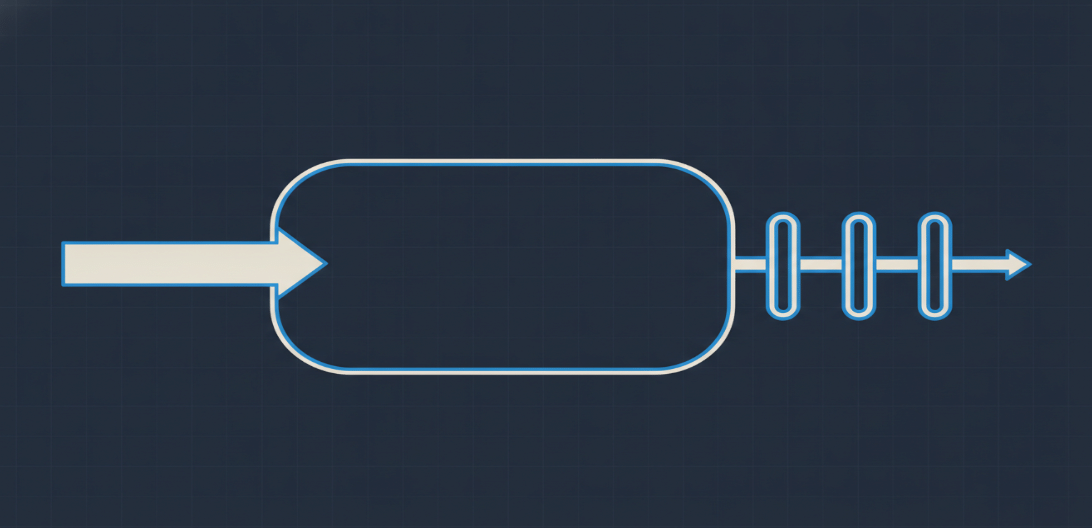
A wide unobstructed inward arrow beside a narrow outward arrow passing gates
Deposits are easy everywhere. Withdrawals are where the terms do their work, and they are where the differences between platforms actually live.
Look for the conditions under which a withdrawal can be delayed or refused, the verification thresholds that trigger additional requirements, and whether those requirements can be satisfied with documents you already have. A platform that requires proof of source of funds above a certain amount is behaving normally. One that introduces the requirement only at the withdrawal stage, without stating it in advance, has designed a friction point rather than a control.
The practical test is cheap. Deposit, complete verification fully, and withdraw a small amount before doing anything else. What that sequence costs in fees is the least expensive information available about the platform.
Review distribution tells you more than the rating
A rating is a single number that a campaign can move. The distribution behind it is considerably harder to manufacture.
What to look at: whether reviews arrive steadily or in clusters, whether the negative ones describe the same failure repeatedly or scatter across unrelated issues, and whether the operator responds with specifics or with a template. A cluster of praise dated within one week of each other, in similar phrasing, is a pattern, not a coincidence.
The property that matters here is that the subject of a review has no ability to take it down. The record is therefore not curated by the party being assessed, which is the condition under which a distribution means anything at all.
The signals that do not survive scrutiny
Several widely cited indicators carry much less information than their prominence suggests.
A secure connection tells you the traffic is encrypted. It says nothing about who operates the site, and certificates are trivially available to anyone.
Volume figures and user counts published by the platform are self-reported and unaudited. They may be accurate. There is no way to tell from the outside, so they are unusable as evidence.
Media coverage is worth checking rather than counting. A platform listed in sponsored roundups has bought placements, which is legal and common and tells you about its marketing budget rather than about its operations. The useful version of this check is to look for coverage the platform did not commission, and to notice when there is none.
Domain age gets cited often and carries less weight than people assume. An old domain can be purchased, and a new one is normal for a new business. It is a weak prior rather than a finding.
What a reasonable pass looks like
Half an hour, in this order. Identify the legal entity and confirm it against a registry. Read the withdrawal terms and note the thresholds. Read the review distribution rather than the rating, and read the negative reviews specifically. Complete a full verification and a small withdrawal before committing anything material.
If the platform fails at the withdrawal step, the remaining questions are academic. If it passes, the remaining risks are the ordinary risks of the asset class, which are a different subject and not one this procedure addresses.
Why the order matters
Every step above is available afterward too. The difference is that a person who has already deposited reads the same evidence differently, because withdrawing has become a cost rather than a test.
That is the whole argument for doing it first. The procedure is not difficult, and the information is not hidden. It simply has to happen while the answer can still change the decision.
It is also worth repeating for platforms already in use. Operators change hands, terms get revised, and a registration current two years ago may no longer be. A once-a-year pass on anything with material value costs an afternoon and occasionally surfaces something that wasn’t true at the last check.